Blog > Second Home Buying in Keauhou: Everything You Need to Know
A second home in Keauhou can be a practical fit when the property's location, ownership costs, association rules, and intended use align with your plans. Buyers may look for a place to return to for family time, future retirement planning, or part-time stays on Hawaiʻi Island.
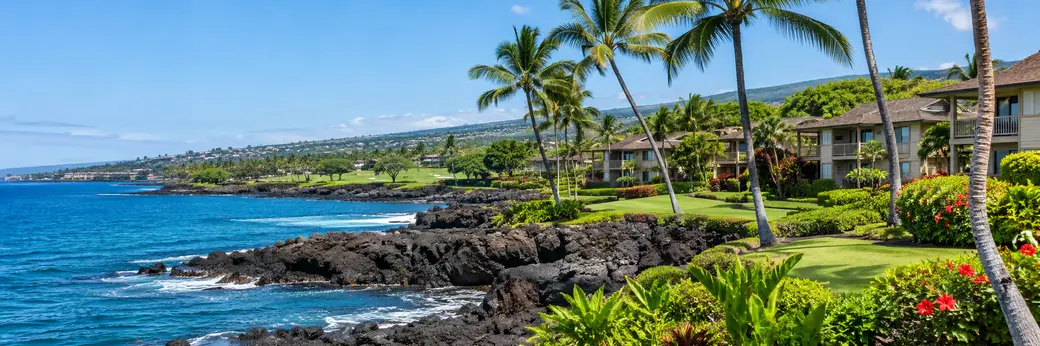
Keauhou is a community at the southern end of Kailua-Kona on Hawaiʻi Island, with condominium, townhome, golf-adjacent, and single-family home options. This guide covers financing, locations, property types, ownership, rentals, and costs for buyers considering a second home in Keauhou, using the most recent 2026 market and tax information available.
Why Buy a Second Home?
A second home can provide a consistent base for personal stays, family visits, future retirement plans, or permitted short-term vacation rental use.
For many buyers, Keauhou combines access to Kailua-Kona services with a range of residential and resort-oriented properties. The right choice depends on how often you expect to use the home, how much maintenance you want to manage, and whether rental use is part of the plan.
Common reasons to buy include:
- Creating a repeat-visit home base instead of arranging accommodations for every trip
- Having space for longer stays and visiting guests
- Planning for future time on Hawaiʻi Island
- Choosing a lock-and-leave condominium rather than a larger property with more individual upkeep
- Considering rental income only where the property, association documents, and applicable rules allow it
Second-home buyers should begin with the ownership experience they want. A condo may suit shorter and more frequent visits, while a townhome or single-family home may better support longer stays, guests, or a future full-time move.
Second Home vs. Investment Property
A second home is primarily intended for personal use, while an investment property is generally acquired mainly to generate income.
That distinction can affect loan terms, down-payment expectations, tax treatment, insurance, and underwriting. A home you plan to occupy regularly may be evaluated differently from one intended for frequent rental activity.
Before making an offer, explain your intended use clearly to your lender, tax professional, and real estate team. A property is not automatically treated as a second home simply because you plan to visit occasionally. Rental frequency, management arrangements, and the property's characteristics can influence how a lender classifies the purchase. For example, lenders generally expect a second home to remain under the owner's control rather than be committed to a rental program that limits personal use.
Ownership structure also deserves attention in Hawaiʻi. Buyers should confirm whether a property is fee simple or leasehold and understand the obligations connected to the interest being purchased. The differences are covered in more detail in this explanation of leasehold and fee simple ownership.
Financing a Second Home
Second-home financing commonly requires a larger upfront commitment and stronger cash reserves than financing a primary residence.
Conventional second-home loans generally require at least 10% down under Fannie Mae guidelines, and many lenders ask for more depending on credit, reserves, and the property. Lenders typically consider credit, debt obligations, available reserves, intended occupancy, property type, and association information for condo purchases. Rates have also moved higher this fall: Freddie Mac's Primary Mortgage Market Survey reported a 7.40% national average for a 30-year fixed loan on October 15, 2026, up from 6.27% a year earlier. Second-home loans may be priced above that benchmark, so an early lender conversation can establish a more realistic search range.
Your preliminary budget should include more than the purchase price:
- Down payment and closing funds
- Monthly principal and interest, if financed
- Property taxes and insurance
- HOA or condominium association dues
- Utilities, maintenance, and periodic repairs
- Travel, furnishing, and setup costs
- Reserves for unexpected ownership expenses
For condo buyers, financing can depend on both personal qualifications and the project's documentation, insurance, budget, and operating characteristics. Giving the project name to a lender early can allow time to review whether it fits the selected loan program.
A mortgage payment estimate is a useful starting point for organizing numbers before property-specific costs are added, and knowing how the loan process unfolds helps when you are coordinating a purchase from out of state.
Choosing the Right Location
The right Keauhou location depends on how you plan to use the home, how often you will visit, and which day-to-day conveniences matter most.
Keauhou is located south of central Kailua-Kona along Aliʻi Drive and includes condominium communities, golf-course surroundings, Keauhou Bay, nearby shopping and dining, and access to the broader Kona Coast. For second-home buyers, travel time to the airport, grocery stores, medical services, beaches, golf, and preferred activities can be as important as a property's view or floor plan.
When comparing locations, consider:
- Your usual arrival and departure schedule
- Whether you prefer a condo, townhome, or detached home
- Elevation, weather conditions, and exposure at the specific address
- Parking, stairs, elevators, and access from the parking area
- Proximity to the places you expect to use regularly
- Community rules, amenities, and maintenance responsibilities
Keauhou may suit buyers seeking a resort-oriented setting close to Kailua-Kona. The Kailua-Kona community overview and West Side property search offer additional context for the surrounding market, and this guide to moving within the Keauhou area covers day-to-day planning in more depth.
Property Types and Options
Keauhou offers several second-home property types, with condominiums and townhome-style residences often appealing to buyers seeking fewer exterior maintenance responsibilities.
A condominium can simplify some aspects of part-time ownership because exterior maintenance, landscaping, and certain shared systems may be handled through the association. That convenience also comes with monthly dues, governing documents, rules, and potential assessments that deserve close review.
Common options include:
- Condominiums with ocean, golf, garden, or mountain orientations
- Townhome-style condominium residences with additional interior space
- Single-family homes with more privacy and individual maintenance responsibility
- Golf-adjacent properties
- Resort-oriented residences with shared amenities
- Oceanfront and ocean-view properties at different price points
Project-level details matter. Two homes in the same community can differ in floor plan, stairs, parking, view corridor, building position, renovation level, monthly fees, and permitted use. Buyers considering condos can compare communities such as Keauhou Resort and Keauhou Punahele, reviewing the governing documents and current property details for each.
Prices and Market Trends in Keauhou
Keauhou pricing varies by property type, project, condition, view, location within a community, and whether the home supports the buyer's intended use. Keauhou-only medians are not published, so the figures below use Kailua-Kona data, which includes Keauhou.
- Condominium median sale price: about $570,000 year to date through September 2026, down 8.1% from a year earlier.
- Single-family median sale price: about $1,194,000 year to date through September 2026, down 5.2%.
- Months of inventory, October 1, 2026: about 8.7 for condominiums and 4.7 for single-family homes.
- Median days on market: 51 days for condominiums and 37 days for single-family homes.
- Price reductions: nearly half of active listings in both segments had at least one price reduction by early October 2026.
Source: Aggregated MLS data for Kailua-Kona.
For second-home buyers, condo inventory near 8.7 months points to a buyer-favorable segment with more selection and negotiating room than in recent years. That said, a broad median is less useful than comparing similar homes in the same condominium project or nearby residential setting. A residence with an ocean view, updated interior, favorable building position, or particular amenity access may be valued differently from another home only minutes away.
Demand can still be shaped by several practical factors:
- Limited inventory within a specific community
- Seasonal second-home interest
- The condition and presentation of individual residences
- HOA dues, reserve planning, and assessment history
- Lending eligibility for a condominium project
- Rental restrictions and operating requirements
Rather than relying on a broad market headline, compare active listings, pending activity, and recent sales that match the property type you are considering. Jennifer's monthly luxury market reports add context for buyers looking at the upper end of the market.
Owning, Managing, and Renting
Part-time ownership works best when you establish a plan for upkeep, access, insurance, and permitted property use before closing.
A second home may be vacant for periods of time, so owners should consider routine monitoring, cleaning, storm preparation, utility oversight, and maintenance coordination. Condominiums can reduce certain exterior responsibilities, but association rules and shared-building obligations remain important.
If you are considering short-term vacation rental use, confirm the specific property's eligibility before relying on projected income. Hawaiʻi County requirements, zoning, association documents, house rules, and private covenants can affect whether and how a home may be rented. Since September 1, 2026, transient vacation rentals of fewer than 180 consecutive days must also be registered with Hawaiʻi County under Ordinance 25-50, with a grace period for existing operators through December 31, 2026. Rental income is also subject to state and county transient accommodations taxes and general excise tax, which belong in any income projection.
A property's listing history or marketing language does not replace written confirmation. Review governing documents carefully and ask about minimum stays, rental caps, registration obligations, guest parking, quiet-hour rules, and any onsite contact requirements. The county's current short-term rental rules are worth reviewing before you narrow a search around rental use.
Jennifer Bien does not provide long-term rental or property-management services. Buyers considering short-term vacation rental use should establish an appropriate local operating plan after confirming that the specific property permits the intended use.
Taxes and Ongoing Expenses
The full cost of a Keauhou second home includes recurring ownership expenses, not only the purchase price and mortgage payment.
Property tax is one of the biggest differences between a primary residence and a second home in Hawaiʻi County. For FY 2027, owner-occupied homes in the Homeowner class are taxed at $5.75 per $1,000 of net taxable value, while non-owner-occupied residences fall under Residential rates of $11.10 per $1,000 (Tier One) and $14.50 (Tier Two). A new Tier Three rate of $17.00 per $1,000 is aimed at non-owner-occupied residences valued above $4 million. Because tax classification follows use, a seller's current tax bill should not be treated as your future cost.
Your ongoing budget should also include insurance, association dues where applicable, utilities, maintenance, furnishings, and reserves for repairs.
For condominiums, request documents explaining what monthly dues cover. Review reserve funding, planned capital work, insurance, prior assessments, and expected maintenance projects. A lower monthly fee is not automatically a better value if the association has substantial future obligations. Comparing what Kailua-Kona condo fees typically include makes it easier to compare buildings side by side.
Insurance also needs early consideration. Coverage availability, deductibles, building characteristics, location, and the condominium association's master policy can influence both the ownership budget and financing options.
The Buying Process Step by Step
A successful second-home purchase starts with a defined budget and ends with a property that supports your intended use.
- Define your use plan. Decide whether the home will be used for personal stays, visiting guests, future retirement, permitted short-term vacation rental activity, or a combination of these goals.
- Set a full ownership budget. Include the down payment, financing, Residential-class property taxes, insurance, HOA dues, utilities, maintenance, furnishings, and reserves.
- Speak with a lender early. Discuss second-home guidelines, reserve expectations, property type, and condo financing considerations before making offers.
- Narrow the location. Compare Keauhou with the parts of Kailua-Kona that fit your travel patterns, preferred activities, and maintenance expectations.
- Review properties at the project level. Compare the building, floor plan, parking, stairs, view, association rules, dues, and current condition, not only listing photos.
- Confirm the ownership and use framework. Review title, association documents, rental restrictions, county registration status, insurance, and other property-specific records.
- Make an informed offer. Structure the offer around the property's condition, current market context, financing needs, and contractual deadlines. With elevated condo inventory, there may be more room to negotiate on price or terms.
- Complete the closing process. Coordinate with your lender, escrow team, and other qualified professionals so you understand final figures, timing, and transfer requirements. Most Hawaiʻi residential escrows close within about 30 to 45 days, depending on financing and contract terms.
A second home in Keauhou works best when your location, budget, property type, and intended use align from the beginning.
For some buyers, that means a lock-and-leave condominium close to Kailua-Kona conveniences. For others, it means a larger townhome or home with space for longer stays and visiting guests. In every case, evaluate the exact property, its association documents, ongoing costs, tax classification, and permitted uses before deciding.
Talk Through Your Keauhou Second-Home Search
Jennifer Bien is a Hawaiʻi licensed real estate broker and REALTOR® with NextHome Paradise Realty in Kailua-Kona, with more than 10 years of experience and the Certified Residential Specialist (CRS) and Certified Luxury Home Marketing Specialist (CLHMS) designations. She works with second-home buyers across Keauhou and Kailua-Kona, from lock-and-leave condos to golf-adjacent and ocean-view residences, and can help you compare buildings, association documents, and ownership costs before you commit. Call or text (808) 938-3052, email jenniferlbien@gmail.com, or reach out here.
FAQ
How much do I need to put down on a second home?
Conventional second-home loans generally require at least 10% down, and many lenders ask for more depending on credit, reserves, property type, and loan program. Discuss financing before setting a purchase range, and plan for closing costs and reserves on top of the down payment.
Can I rent out my second home?
A second home may be available for rental use only when county requirements, zoning, association rules, and governing documents allow the intended activity. Rentals of fewer than 180 consecutive days must also be registered with Hawaiʻi County as of September 1, 2026. Confirm the requirements in writing for the individual property before factoring rental income into your plan.
Is a second home a good investment?
A second home can support long-term ownership goals, although personal use, holding costs, and budget should guide the decision before potential financial returns. Kailua-Kona condo and single-family medians were both lower in 2026 than a year earlier, a reminder that values can adjust. Expenses, market conditions, and rental limitations can all affect the outcome.
How much more is property tax on a second home in Keauhou?
For FY 2027, Hawaiʻi County taxes owner-occupied homes at $5.75 per $1,000 of net taxable value, while second homes fall under Residential rates starting at $11.10 per $1,000. That difference can roughly double the annual tax bill on the same assessed value, so it should be part of your budget from the start.
Can I use a VA or FHA loan for a second home?
VA and FHA financing is generally intended for primary residences rather than second homes. A lender can explain whether your planned occupancy and financial profile fit a particular program.